
Self Assessment / High Income Child Benefit Charge
Discussion


Hi all, I am trying to work out the lie of the land in regards to my attempt at self assessing for the previous year. I got a letter about child benefit charge and self assessment seemed to be the way to sort it. I have never paid the charge before and previously I have been owed money when self assessing.
My yearly taxable income on my March 2026 payslip was £69 so I think I need to pay some back. I don't have a P60 for 2025-2026 as my employer is a waste of space. I also have a tiny amount of income (sub £500) for self employed work elsewhere.
Is the below saying I owe £2091? Also it then asks about putting it into next years tax code, and that's where I have no idea what that means or how it works. I am also just about to start a new job which is much less pay at first so can't afford any deductions or reductions. I thought of paying a tax adviser to complete the form but that seems counter productive as I can't see what difference that will make other than additional money being paid for their service.
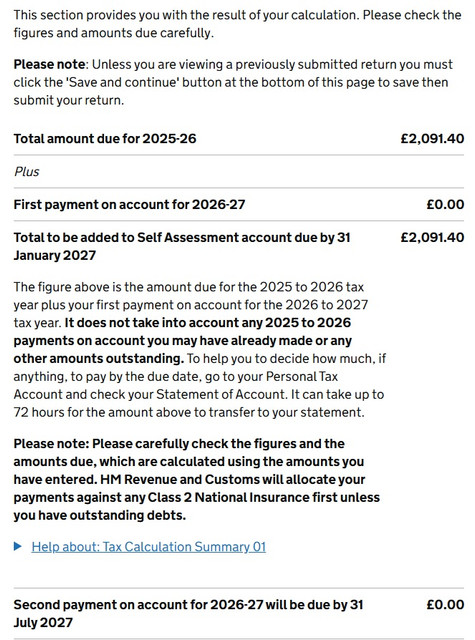
My yearly taxable income on my March 2026 payslip was £69 so I think I need to pay some back. I don't have a P60 for 2025-2026 as my employer is a waste of space. I also have a tiny amount of income (sub £500) for self employed work elsewhere.
Is the below saying I owe £2091? Also it then asks about putting it into next years tax code, and that's where I have no idea what that means or how it works. I am also just about to start a new job which is much less pay at first so can't afford any deductions or reductions. I thought of paying a tax adviser to complete the form but that seems counter productive as I can't see what difference that will make other than additional money being paid for their service.
I think your right, it's saying you owe £2091 by the end of January. Although that seems alot of child benefit to pay back. How much do you receive in children benefit each year?
If you request your tax code to be changed it means you will pay more tax each month for this tax year.
You say you are earning less now. are you just over £60k? If so you could pay a bit more into salary sacrifice pensions if your new employer does them to bring yourself below £60k and avoid paying high income child benefit charge.
My overtime put me at 69k taxable for the previous year - we claim for 2 kids so that's pretty much 100% of it as far as I know. I don't mind paying it back in tax but I am about to start a new job which will be less than half my current income for 6 months and I am conscious of everything getting squiffy with tax codes etc. I will have 2 pay slips in November which I am told will already cause issues.
That seems a hell of a high charge unless you’ve got a lot of kids or it’s somehow more than one year’s repayments. Just checked and we’re getting £2337.40 for 2 kids (£179.80 x 13 because the DWP works on 4 weeks rather than months), £69k taxable income should put just below the middle of the repayment scale (£60-80k after Hunt was shamed into increasing it from £50-60k).
Have you declared a lot of additional income from bank accounts or something? As others have said, look at Salary Sacrifice to try to reduce your taxable income and liability if possible. Similarly, try to get as much of your savings into ISAs.
Have you declared a lot of additional income from bank accounts or something? As others have said, look at Salary Sacrifice to try to reduce your taxable income and liability if possible. Similarly, try to get as much of your savings into ISAs.
Ubiquitous2024 said:
That's what I am unsure about - payslip was 77 gross, 69 taxable. Its a police pension so I pay £700 a month into it. But that's all about to finish anyway.
£700/month would be £8400, so those figures pretty much add up. Have you definitely entered the correct figures into the self-assessment? I’d expect your P60 would show the £69k figure as your pre-tax total and that would be what was declared on your self-assessment.Do you know if we’re talking about one year’s repayments here or more? Also, how many kids have you got/how much did you receive in child benefit over that tax year?
Edited by alangla on Monday 12th October 13:56
Your employer is breaking the law if they have not yet provided you with a P60 for tax year 2025/26. It is now just over six months since the tax year ended.
INSIST that they give it to you.
Have they set up an employee "portal" page for you?
Many employers these dasys do not issue a paper P60 or even a pdf version. Instead, they provide the employee with an online link which allows them to view and save P60s, payslips etc.
INSIST that they give it to you.
Have they set up an employee "portal" page for you?
Many employers these dasys do not issue a paper P60 or even a pdf version. Instead, they provide the employee with an online link which allows them to view and save P60s, payslips etc.
I managed to get my last P60 by emailing HR and awaiting the response (its all outsourced and you cant contact anybody direct) so I do have it. But all this and related admin is all non functioning in my job - bottom of the barrell cost cutting outsourced offer the bare minimum service - hence why things like this and pension stuff are so difficult (we also have inaccurate annual pension statements for the last 3 years).
I can't see a way out of paying this so will just have to say take it out my tax. But not sure how that will work when my wage drops by 50%.
I can't see a way out of paying this so will just have to say take it out my tax. But not sure how that will work when my wage drops by 50%.
Go back into the self assessment and check every single figure you ve entered. My guess is that you’ve declared £77k as your taxable income when it should have been £69k if that’s your P60 figure. Also check each and every non-ISA bank account you have for the tax certificate & add it up on the spreadsheet that links off the self assessment. Your demand fits with a declaration of £77891, though that’s based on this year’s rate of payment, 2025-6 would have been a few percent lower, though I don’t have the figure to hand.
Edited by alangla on Monday 12th October 20:56
That's one way of doing it.
Of course, if you circumstances change i.e. your income for any reason drops BELOW the "claw back" threshold, you need to contact HMRC IMMEDIATELY otherwise you will be paying back Child Benefit you were actually entitled to keep. If you inadvertantly don't claim Child Benefit when you could have, HMRC will NOT give you back any clawed back Child Benefit they shouldn't really have had.
Of course, if you circumstances change i.e. your income for any reason drops BELOW the "claw back" threshold, you need to contact HMRC IMMEDIATELY otherwise you will be paying back Child Benefit you were actually entitled to keep. If you inadvertantly don't claim Child Benefit when you could have, HMRC will NOT give you back any clawed back Child Benefit they shouldn't really have had.
Eric Mc said:
That's one way of doing it.
Of course, if you circumstances change i.e. your income for any reason drops BELOW the "claw back" threshold, you need to contact HMRC IMMEDIATELY otherwise you will be paying back Child Benefit you were actually entitled to keep. If you inadvertantly don't claim Child Benefit when you could have, HMRC will NOT give you back any clawed back Child Benefit they shouldn't really have had.
Thats exactly what will be happening this year, however this is from last year. I am about to go from 70k a year to 38k next month. Of course, if you circumstances change i.e. your income for any reason drops BELOW the "claw back" threshold, you need to contact HMRC IMMEDIATELY otherwise you will be paying back Child Benefit you were actually entitled to keep. If you inadvertantly don't claim Child Benefit when you could have, HMRC will NOT give you back any clawed back Child Benefit they shouldn't really have had.
Make sure they don't take back any Child Benefit from you that shouldn't be getting.
The problem HMRC has is that they are usually operating from information based on the previous (or sometimes even earlier) tax year which means they may be doing something that isn't correct for the current tax year.
The problem HMRC has is that they are usually operating from information based on the previous (or sometimes even earlier) tax year which means they may be doing something that isn't correct for the current tax year.
Gassing Station | Finance | Top of Page | What's New | My Stuff